Ripple Targets Cross-Border Payments With Liquidity Tools and AI Forecasting
Checked out by Neil C. Hughes · 854 reads
Ripple sees blockchain as a way to improve cross-border payments, but says liquidity, forecasting and standard access tools remain key hurdles.
Ripple’s case for blockchain in payments depends on more than faster settlement. The company argues that digital asset services need dependable liquidity, forecasting and connections between traditional money and crypto before they can deliver reliable cross-border transfers at scale. Brad Chase, Ripple’s Head of Liquidity Products, sees those capabilities as infrastructure that can serve payment firms today and other businesses as they adopt digital assets.
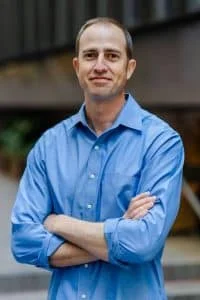
Brad Chase.
The opportunity is large: Chase describes cross-border payments as a $130 trillion market. But the figure frames the scale of the problem, not a measure of Ripple’s current business. His central point is that blockchain may make transfers more visible and easier to track, while the liquidity needed to support those transfers still largely sits in established financial systems.
Modernizing payment infrastructure means solving for liquidity
Chase says much of the financial infrastructure underpinning international transfers dates to the 1970s. That legacy makes it difficult to move and settle money with the speed, visibility and traceability people expect from digital services. Ripple’s view is that blockchain and digital assets can help address those limits through a shared record of transactions that remains available to network participants.
Yet a new settlement layer cannot deliver a useful payment on its own. Customers also need access to funds on both sides of a transfer, and the pools of liquidity supporting traditional finance have not automatically shifted into crypto markets. Those markets are newer and smaller by comparison, Chase says. The operational challenge is to connect the systems while keeping transfers dependable and affordable for payment customers.
Chase describes the $130 trillion cross-border payments market as a major opportunity for blockchain’s “single source of truth” and its open, distributed, always available design.
That framing puts liquidity management at the center of Ripple’s product strategy. The customer sees a payment; behind it, a provider must source assets, manage exchange-rate exposure and complete the transfer across different financial rails. If any part of that chain is unreliable or costly, the underlying technology does little to improve the experience.
Payment products as a foundation for other uses
Ripple has spent years building trading platforms, integrations, partnerships and compliance services to support liquidity for its payment products. Chase says that work takes time, and argues that companies in crypto have not always built these operational pieces before pursuing new use cases. With them in place, Ripple can serve remittance firms that need to move money across borders, then apply parts of the same infrastructure to other businesses.
For example, a retailer selling luxury goods might want to accept stablecoins or offer non-fungible tokens. That business would still need ways to manage liquidity and connect customers using conventional money with digital asset services. Chase’s point is that these needs overlap: systems developed to support payments can become building blocks for other customer workflows.
The approach also lets infrastructure develop alongside demand. As a company solves one customer problem, it may identify a capability needed by the next use case. Ripple sees that process as a way to extend its payment systems and mature the surrounding crypto ecosystem. The claim is a strategic one; the interview does not provide comparative performance data or a breakdown of the cost and reliability gains from these investments.
AI helps make liquidity decisions at scale
Ripple already uses artificial intelligence and machine learning to forecast customer demand for assets and plan liquidity, Chase says. He describes a workload involving 27 million payments and $50 billion in cross-border transfers. At that volume, simple rules may not be enough to account for factors such as exchange-rate volatility and changing market supply.
Forecasts help the company estimate what customers will need, then weigh choices that can reduce costs while preserving resilience. Chase characterizes the system as a logistics platform: forecasting, planning and execution work together to support consistent service. His background in high-frequency trading, where he spent close to a decade managing quantitative development and trading strategy research teams, informs his view that similar forecasting and risk-management methods apply to payments.
The interview offers no model details, accuracy figures or cost comparisons, so the scale figures describe the payment activity at issue rather than a benchmark for the AI systems themselves. The practical case is that automation can help coordinate many decisions quickly and consistently; it does not remove uncertainty in markets or eliminate the need to manage risk.
Blockchain may also support AI provenance
Chase sees possible links between blockchain and generative AI beyond payments. As language models produce more content, questions about authenticity, provenance and copyright become more pressing for users and businesses. A shared ledger could help record information about content and make that history available across parties that lack prior agreements.
That is a prospective use, not a deployed product described in the interview. Blockchain can provide a shared record, but the value of that record depends on how information enters the system and whether users trust the process. Chase’s broader observation is that technologies can take years to move from early development into ordinary products. He sees crypto at a similar stage of integration.
Adoption depends on standard access and operating tools
Chase expects more institutional use of digital assets, pointing to the prior year’s ETF approvals as one sign of growing interest. He argues that crypto’s persistence through repeated cycles has helped some institutions consider it as a tool for problems such as cross-border transfers. In his view, wider institutional participation and stronger compliance processes could support greater stability, which may in turn attract more participants.
He also expects broader tokenization: representing real-world assets, such as real estate or financial instruments, on a blockchain. The proposed benefit is more efficient operations and management, with institutions able to build on infrastructure that was less developed three to five years ago. The interview does not specify which assets or workflows are already operating at scale.
For Chase, the near-term building blocks are on- and off-ramps, identity systems and compliance services that businesses can use as standard infrastructure. Ripple’s LiquidityHub experience has reinforced the role of those connections, he says. If they become easier to access and operate, businesses may eventually treat digital asset rails as a routine part of their services rather than a defining feature of the company.
That is the practical test for Ripple’s thesis: blockchain needs enough liquidity and dependable connections to deliver payments customers can use, while forecasting systems keep costs and risk manageable. Adoption will hinge on whether those operational pieces work across real customer needs, not on the ledger alone.